

A tumultuous 2025, a looming LNG supply glut and plummeting prices are re-shaping the investment prospects for the global LNG business. But short-term turmoil belies robust fundamentals, with the long-term outlook brighter than it was six months ago.
Gas Strategies published its LNG Outlook 2025 just as Donald Trump was being inaugurated as the 47th POTUS. In the six months since he returned to the White House, US President Donald Trump has dominated headlines around the world.
Our Mid-Year Focus 2025 picks up where our LNG Outlook 2025 left off.
Highlights
The energy industry, in the thick of it, is having to contend with unusual degrees of volatility and uncertainty. This applies especially to LNG – an integrated global business, high in value but also high in risk, susceptible not just to tariffs per se but also their inflationary impact. How should investors, financiers, producers, sellers and buyers be responding?
Gas Strategies’ LNG supply-demand balance, 2023-2050 (as at July 2025)
Source: Gas Strategies
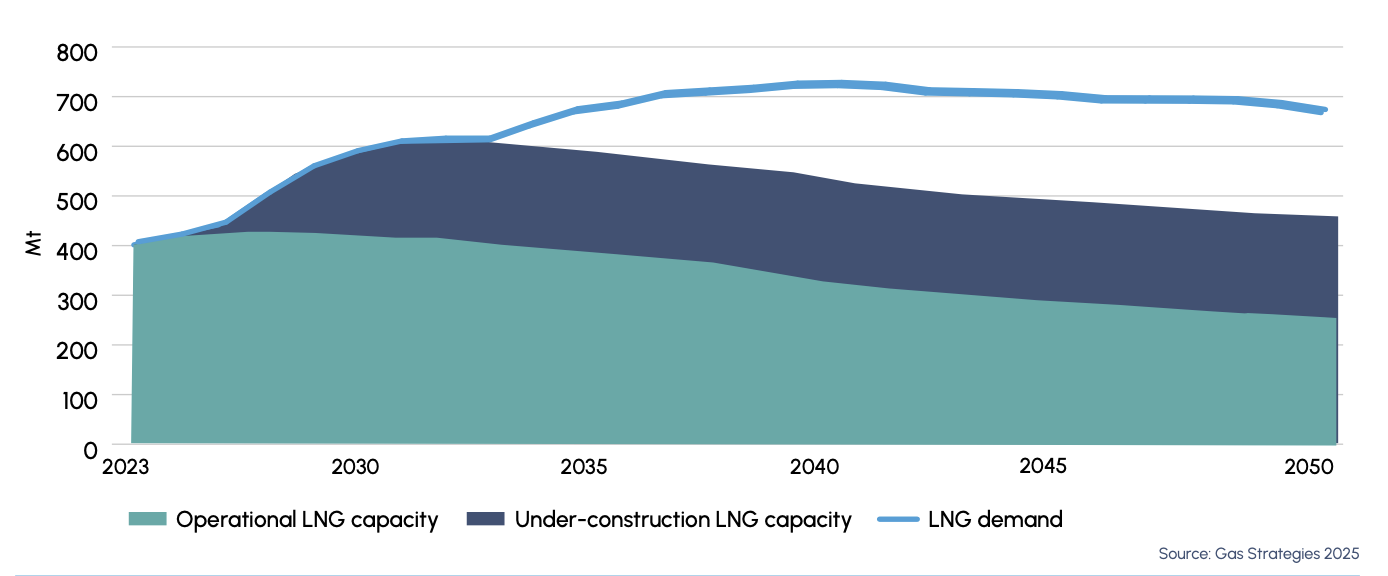
- Between now and the end of the decade, some 180 mtpa of projects already under construction are due to come onstream, boosting global production capacity by around half to 600 mtpa
- For now, there remains a possibility that the peak in global LNG demand may recede into the 2040s
The scale of future investment needs depends on retirements: The extend of this need for new investment will depend in part on how quickly ageing operational liquefaction is retired. Liquefaction plants tend to outlast their expected lives, moreover, refurbishment can be more cost-effective than building new ones - The energy transition shows signs of losing momentum; anti-climate action policies of President Trump have been introduced and clean energy technologies outside the electricity generation sector are struggling to deliver
- Gas Strategies expects spot LNG prices to fall sharply as the new wave of supply builds. The annual JKM price could get down to around $7/MMBtu
Out of the 180 mtpa of LNG capacity currently under construction, up to 110 mtpa is being underpinned by companies with no gas consumption of their own.
Stay ahead of the turbulence reshaping the LNG business.